Mandatory insurance is the largest deduction on a payslip after tax, and the easiest to get wrong because the contribution base is not net pay and because each fund has different caps.
What you need to know first
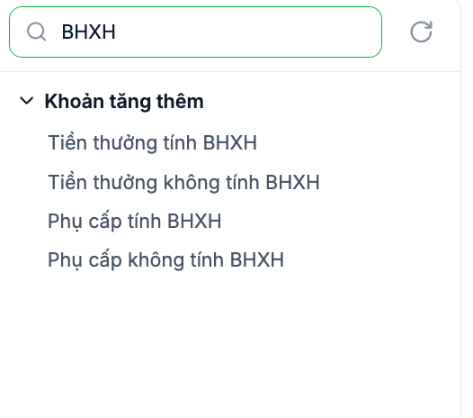
The system has no variable that calculates the insurance amount payable. Searching for "insurance" in the variable library returns no results. All that's available are four income classification variables: Allowances subject to social insurance · Allowances not subject to social insurance · Bonuses subject to social insurance · Bonuses not subject to social insurance. This means the insurance deduction columns must be built by the company itself using formulas, including the handling of caps and floors. We have reported this to the product team.
Three concepts not to confuse
| Concept | What it is |
|---|---|
| Net pay | The amount deposited into the account. It is not the insurance contribution base |
| Salary stated in the contract | May or may not be the same as the insurance contribution base |
| Salary used as the basis for insurance contributions | A separate concept defined by law — this is the actual contribution base |
Confusing these three concepts is the most common mistake in the industry. The insurance contribution base usually consists of the job-based salary plus certain fixed allowances, and excludes items that vary with productivity or work results.
How to build the deduction columns
- Set up allowances in Salary Grades, clearly classifying which ones count toward the insurance base (article B9-03).
- In the payroll template, create an Insurance contribution base column = base salary + allowances subject to social insurance.
- Create a Base after cap column that applies the caps and floors per regulations.
- Create deduction columns for each fund, each multiplying the base after cap by the corresponding rate.
- Create a Total insurance deductions column that sums the columns above.
Don't embed rates and caps directly inside formulas. Set them up as separate columns or as items in Salary Grades, so that when regulations change you only need to edit one place instead of hunting through every template for every branch.
Reference figures — Vietnam
The section below applies only to companies operating in Vietnam. Companies in other countries should skip it and substitute local regulations.
| Fund | Employee | Employer | Total |
|---|---|---|---|
| Retirement and survivorship | 8% | 14% | 22% |
| Sickness and maternity | — | 3% | 3% |
| Occupational accidents and diseases | — | 0.5% | 0.5% |
| Health insurance | 1.5% | 3% | 4.5% |
| Unemployment insurance | 1% | 1% | 2% |
| Total | 10.5% | 21.5% | 32% |
Legal basis: Articles 32, 33, 34 of the 2024 Law on Social Insurance (No. 41/2024/QH15) · Article 33 of the 2025 Law on Employment · Article 6 of Decree 188/2025/ND-CP · Article 43 of Decree 158/2025/ND-CP. Figures verified as of 07/27/2026.
- Foreign workers: 30% total (employee 9.5% + employer 20.5%) — not subject to unemployment insurance contributions.
- Occupational accidents and diseases fund: 0.5% is the standard rate. A lower rate applies only when the company submits an application and meets the conditions — it is not automatic.
Caps and floors — Vietnam
| Type | Cap basis | Until 06/30/2026 | From 07/01/2026 |
|---|---|---|---|
| Social insurance and health insurance | 20 × reference level | 46,800,000 VND | 50,600,000 VND |
| Unemployment insurance | 20 × regional minimum wage | Region I 106,200,000 · II 94,600,000 · III 82,800,000 · IV 74,000,000 | Unchanged in 2026 |
| Floor (enterprise sector) | Regional minimum wage | 3,700,000 – 5,310,000 depending on region | Unchanged |
Reference level from 07/01/2026: 2,530,000 VND/month — Decree 161/2026/ND-CP dated 05/15/2026. 2026 regional minimum wage — Decree 293/2025/ND-CP dated 11/10/2025, effective 01/01/2026.
There are three different caps, not one. The unemployment insurance cap is based on the regional minimum wage, so it differs between regions and is entirely different from the social insurance cap. Multiplying the 32% total by a single cap is incorrect for every employee earning roughly 50 million or more. This is why you must build a separate cap column for each group of funds.
The contribution floor for the enterprise sector is the regional minimum wage, not the reference level — because companies may not pay less than the regional minimum wage. Many materials on the market get this point wrong.
Formal requirements for excluding an item
In Vietnam, benefits that are excluded from the insurance contribution base may only be excluded when they are listed as a separate item in the employment contract. A fuel allowance paid as a fixed monthly amount but lumped into the salary item is still counted toward the base. The name doesn't decide it — how it is written in the contract and the nature of the payment do.
The figures in this article were verified as of 07/27/2026. Insurance regulations change frequently, especially at the January 1 and July 1 milestones each year. The legal or accounting department must review them before each documentation update, and the company bears sole responsibility for the calculation method it applies.

